Image by Red Dot on Unsplash
I am going through writer's block. Too many ideas, that's my version of it. Notebooks full of half finished themes, and a shortlist that came down to two: the current bond crisis, and how democracy should work.
Image by Ryan Snaadt on Unsplash
Then it hit me: these aren't two topics. In my opinion, one causes the other. The way we run our democracies is why we have a bond crisis. So I'm splitting it into two posts.
This one is on democracy, specifically, on why I think our current ideas about democracy deserve to be challenged, not inherited as settled fact. The followup will be on the bond crisis, where the bill for all of this is finally landing.
The flaw in the machine
Analysts look for incentive structures, so let me describe the one we live under. A politician manufactures promises. The voter consumes them at zero cost at the point of sale. The bill goes to a third party: tomorrows taxpayer, today's bondholder. Nobody in the transaction has a reason to ask the price.
There is a quote I keep coming back to, attributed to the 18th century Scottish historian Alexander Fraser Tytler:
"A democracy cannot exist as a permanent form of government. It can only exist until the voters discover that they can vote themselves largesse from the public treasury. From that moment on, the majority always votes for the candidates promising the most benefits from the public treasury..."
I'll be straight: the attribution is disputed, nobody has found the passage in Tytler's known works. Doesn't matter. My job is to test whether something is true, not whether the label is right. And this observation, that the public will always vote for the politicians who give them “stuff”, has been validated by fifty years of “public choice” economics. When the cost of promises is deferred and the benefit is immediate, the demand for promises is infinite. That is not a moral failing of voters. It is arithmetic.
The fastest experiment ever run
When I hit writer's block, I reread old books. The one I keep coming back to for this post is The Great Betrayal, the memoirs of Ian Douglas Smith, Rhodesia's last Prime Minister. It's usually filed under controversial history. I file it under forecasting, because as a prediction document it has one of the best hit rates I have ever read.
Smith's argument was never really about who should rule. It was about who should be licensed to vote themselves the treasury. His term was responsible majority rule:
"What we believed in was responsible majority rule as opposed to irresponsible majority rule... I think it's important that before you give a person a [right to] vote you ensure that his roots go down [and] that he's part of the whole structure of the country."
And in 1979, on the handover:
"Pushing people forward simply because of their colour, irrespective of merit, would be most unfortunate and would of course lead to disaster. It would mean that Rhodesia would then develop into a kind of banana republic where the country would in no time be bankrupt."
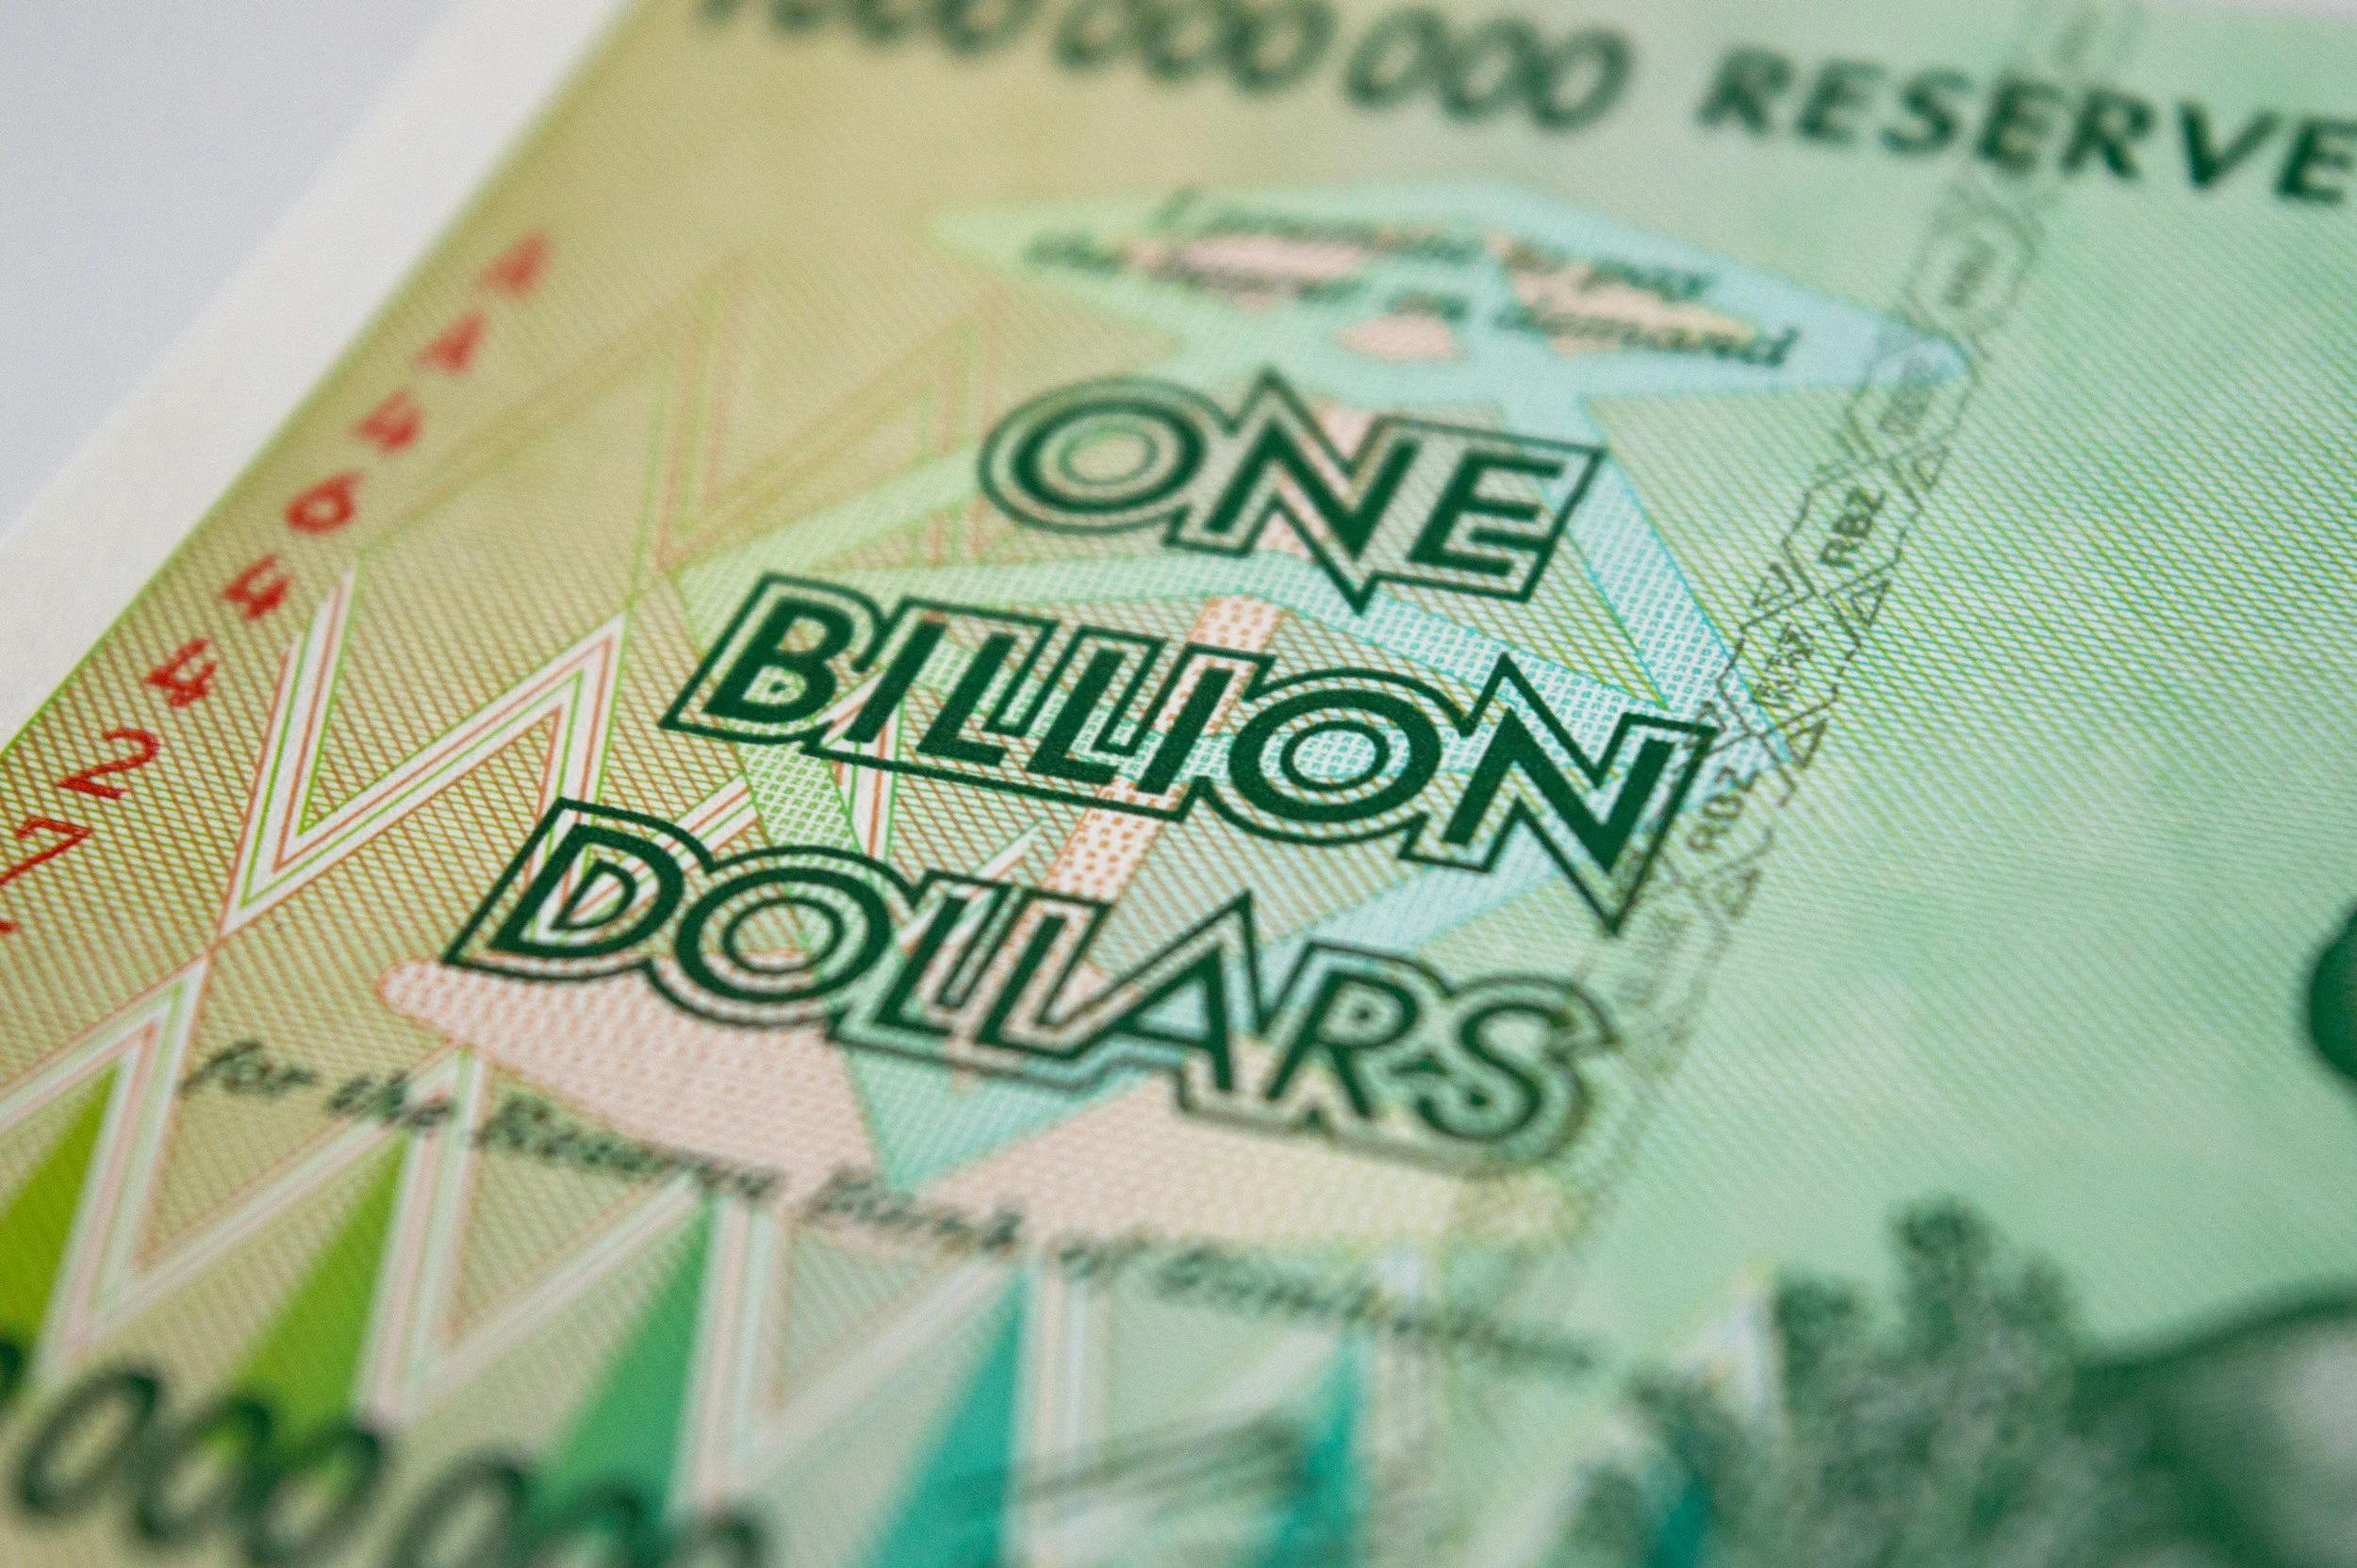
Image by Rob on Unsplash
Now run that quote against the data.
It is 2026, and Zimbabwe is the banana republic. Under Smith, inflation and interest rates ran below 3% and the Rhodesian dollar stood on par with sterling. Then came the “one man, one vote” settlement, applied overnight to an electorate with no stake in the system. And what did it deliver, exactly and immediately?
The man who promised the most stuff. Robert Mugabe won power on promises (land from other people, gratuities from the Treasury) and when the till ran dry, he printed.
The unbudgeted war veteran payouts of 1997 crashed the currency in a single day ("Black Friday"), and that was before anyone had heard of sanctions. The “vote for stuff” machine ran to its logical conclusion: by November 2008, annual inflation peaked at 89.7 sextillion percent, prices doubling overnight, and a $100 trillion banknote wouldn't cover the bus fare. In 2009 the currency was abandoned altogether. The country that was one of the richest and most orderly economies in Africa, ended up with the second most severe hyperinflation in recorded history within a single generation.
And the political ledger? One man, one vote, one party, one dictator. An estimated 20,000 dead in Matabeleland in the 1980s. Elections as ritual. Smith warned that majority rule handed to an electorate with no roots in the system would end in disaster and bankruptcy, and it ended in disaster and bankruptcy, on schedule and in order.
Even Zimbabwe's own opposition came to see it. Morgan Tsvangirai, the man who led the fight against Mugabe and suffered for it:
"If Smith was a black man, I would say that he was the best Prime Minister that Zimbabwe ever had."
And Patrick Kombayi, a former opposition mayor:
"The roads that we are using today were all built by Smith... When he left power the pound was on a par with the Zimbabwean dollar, but President Mugabe has killed all that."
Not about colour. Not about minority rule.
Before we go further, let me be precise about what this post is arguing, because it is easy to misread it as nostalgia for a racial order, and it isn't.
This has nothing to do with colour. And it is not a brief for minority rule. Rhodesia appears in this argument for one reason only: it is the only modern case where the franchise was deliberately tied to demonstrated stake rather than simple existence, and the only case where we can watch what happens when that tie is cut, overnight, with the “before and after” data intact. It is a natural experiment on the franchise, not a case study in who should hold power.
The argument travels to any electorate of any composition, anywhere. Apply it to Britain, France or America today and the test is identical: net contribution, measured over a lifetime, in pounds, euros or dollars: not skin. Indeed, the whole point of doing this with modern tax data is that the test can finally be impersonal: a spreadsheet, not a gatekeeper. The principle is stake!
And that is the real target of this post: the assumption that our current franchise is the final form of democracy, that "one adult, one vote" is an endpoint reached in 1918 or 1928 or 1965, and that anyone who questions it must be questioning people rather than structure. Universal suffrage as we know it is barely a century old. It is not a law of physics. It is a design choice, one of several the modern era has tried, and the balance sheets suggest it has an inherent failure mode. Design choices can be revisited. That is what this post is doing.
A vote you earn
So what's the fix? The one principle that could actually break the Tytler problem: contribution before franchise. If you pay in more than you take out, you are a shareholder in the enterprise. If you take out more than you pay in, giving you an equal say on the dividend is (in corporate terms) a governance scandal. Smith's "responsible majority rule" was that principle, half a century ahead of the technology needed to run it fairly. We now have that technology.
How it should be done
This is where most people reach for easy slogans ("no representation without taxation") and stop. Here's how I'd actually design it:
1. Net contributor status, on a rolling window. Your full franchise depends on being a net contributor to the public purse over, say, five of the last ten years: direct taxes paid exceeding transfers received. Governments already hold most of this data.
2. Measure contribution over a lifetime, not a snapshot. Pensioners who paid in for forty years keep their vote, full stop. This answers the lazy objection that a contribution franchise "disenfranchises old people." A lifetime net contribution ledger protects precisely the people who carried the system on their backs.
3. Count the contributions that never show up on a payslip. Years of military or public service, full time caregiving, raising the next cohort of taxpayers are all capital contributions to the system. They should earn contribution credits.
4. If a binary franchise is too radical, weight the vote. Everyone keeps a vote, but unbalanced budgets (spending bills that must be funded by borrowing) require a supermajority of net contributors. The Swiss debt brake and the German Schuldenbremse prove democracies can legislate against their own fiscal appetites. Same idea, softer edges.
5. Keep the test arithmetic, not judgmental. The design rule that makes the whole thing legitimate: contribution is a number, not an opinion. Net tax position over a rolling window, published thresholds, no discretion, no officials deciding who "deserves" a say. Run it by the tax authority's computers and it stays a principle. Hand it to a committee and it becomes a lever.
What this has to do with the bond market
Notice what all of this is really about: aligning the vote with the balance sheet. Under our current franchise, the marginal voter's incentive is to vote for the politician who gives them stuff, and the marginal politician's incentive is to buy votes with money the state doesn't have. The bond market is the only constituency that cannot be bought with promises, it demands actual cash, on actual dates, with actual interest. So when the “vote for stuff” equilibrium reaches its limit, the bond market is where it breaks.
Zimbabwe proved it in fast forward. The West are running the same experiment in slow motion and the breaking point has started to arrive. This month, UK ten year gilt yields hit their highest level since July 2007, with thirty year yields dragging pension funds back into the headlines. The bond market is now doing the job our democracies refused to do: saying no to the “vote for stuff” machine. That's the bond crisis, and it's the subject of the followup post.
Sources: Ian Smith quotes via Wikiquote (including the Tsvangirai quote and the Kombayi quote, the latter from The Telegraph, 2007); the Tytler attributed quote and its disputed provenance via Snopes; hyperinflation figures (89.7 sextillion percent, prices doubling every 24.7 hours) via the Cato Institute and Wikipedia; current gilt levels via Reuters and Trading Economics; book details via Wikipedia.
DISCLAIMER
This publication is general in nature and is not intended to constitute any professional advice or an offer or solicitation to buy or sell any financial or investment products. You should seek separate professional advice before taking any action in relation to the matters dealt with in this publication. Please also note our disclosure here